

- The Tesco share price gains for the 9th straigh day, but signs of exhaustion in the share price are starting to show.
Current Setup
The Tesco share price continues to push higher after the company reported a stellar first-half earnings performance for the 26 weeks ended 29 August 2026. The company also raised its full-year adjusted profit guidance, raising the lower end of its prior guidance and increasing the size of its share buyback program.
The stock is up 0.78% as of writing, marking the ninth straight day of gains after the profit guidance upgrade. The stock is currently quoted at 543.4, up about 22% since the start of 2026. This also puts the stock at the top of its supported 52-week range.
The current investment debate centers on whether the company’s improved profitability and cash generation can be sustained amid more competitive pricing for grocery products among its peers, cost pressures, and uncertainty about household spending (due to higher costs of goods and services). These increases directly reflect higher energy prices, which are pushing inflation through the UK grocery supply chain and in many other countries.
Tesco Share Price: Key Macro Drivers
1. H1 Results Exceed Expectations
Tesco reported adjusted operating profit of £1.783 billion, up 6.5% year-on-year. Sales excluding VAT and fuel rose 2.0% to £33.8 billion, while adjusted diluted earnings per share increased 12.2% to 17.3p. UK like-for-like sales grew 1.5% in the first half, with UK food sales increasing 2.4%. The figures indicate that Tesco continues to benefit from its scale, value proposition and position in essential household spending.
The next major test is whether Tesco can meet its upgraded profit outlook target in the second fiscal and during the upcoming shopping season.
2. Upgraded Profit Guidance and Share Buybacks
The upgraded profit guidance has been critical to Tesco’s bullish share price performance. The company raised the lower end of its full-year adjusted operating profit forecast range to £3.15 billion (previously £3.0 billion), while retaining the upper limit of £3.30 billion.
Tesco also expanded its 2026 share buyback program from £750 million to £950 million, supported by its improved cash generation. The interim dividend was raised by 5.2% to 5.05p per share.These measures have made the company stock the toast of investors, as these support the shareholder-return case.
3. Competition, Higher Costs and Consumer Spending Pressure
Tesco reported UK like-for-like sales as having grown 1.5% in H1 (January 6), with food sales in the UK rising 2.4%. Tesco also reported a 6.5% year-on-year increase in adjusted operating profit to £1.783 billion. Sales, not including value-added tax and fuel costs, climbed 2.0% to £3.8 billion while the company’s adjusted diluted earnings per share rose 3.2% to 17.3p. The data indicates Tesco continues to benefit from scaling operations, an improved value position, and its premium positioning within the UK’s essential household spending budgets.
The company continues to face rising competition from other market players such as Aldi, Lidl, and Sainsbury’s. The company must balance maintaining its price position with protecting margins as household budgets come under pressure from rising costs driven by geopolitically motivated imported inflation.
The company grew online sales by 8% while expanding its rapid delivery Whoosh service by 7%. These expansions have created additional growth opportunities. However, the execution and profitability of these expanded income channels will remain critical to the company’s ability to retain its market share in the UK grocery market.
Tesco Share Price: Forecast Scenarios
Bull case: Continued momentum from the share buyback, earnings report, and positive narratives could support a breakout above 540p, then expose targets at 550p or higher.
Base case: If the market continues to digest the earnings upgrade and other news while balancing these against cash generation, future sales growth, and costs, we could see consolidation between 510p and 550p.
Bear case: The sharp upside move looks overdue for a retracement. If profit-taking or sour sentiment from consumer-spending pressures or competitor discounting occurs, this could drive a sustained move below 510p. In this scenario, a leg lower to 495p cannot be ruled out.
Technical outlook
The push toward 543.8 is now complete, and a retracement from here must first take out the 502.0 support (24 February and 29 July highs) before the 484.2 support is reached. Below this level, additional downside targets are 464.1 and 455.2.
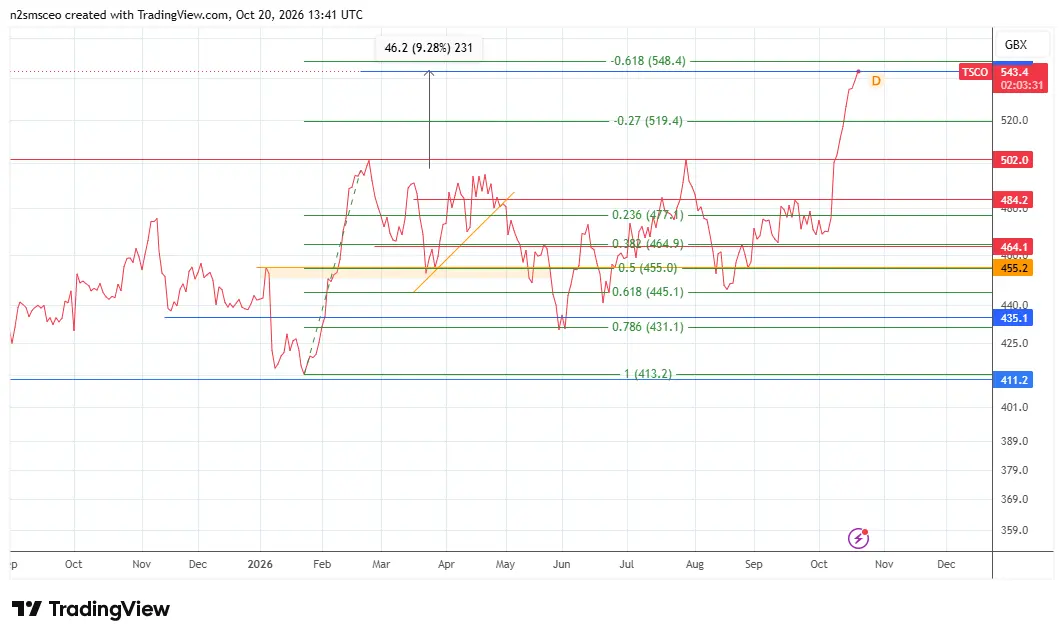
Conversely, a break of the 543.8 resistance brings new upside targets at 580.4 (100% Fibonacci level) and 615.0 (141.4% Fibonacci level).