

- Micron Technology has a forward price-to-earnings ratio of 5.
- It is one of the cheapest S&P 500 stocks this year.
- The Wyckoff Theory suggests that it has more downside risk.
Micron stock has sold off since June as investors have sold off memory companies despite their strong revenue and profitable growth. MU dropped to $880, down by over 30% from its all-time high. This retreat has made it one of the cheapest companies in the S&P 500 Index. Still, the Wyckoff Theory suggests that the stock has more downside to go.
Micron is One of the Cheapest S&P 500 Stocks Despite its Revenue Growth
In an ideal situation, Micron would be one of the most expensive companies in the S&P 500 Index. Besides, it is one of the fastest-growing companies, with the recent results showing that its revenue soared by 379% in the fourth quarter to $54 billion, with its gross margin spiking to 86%.
Micron also boosted its forward guidance, with analysts expecting that its annual revenue will soar to $275 billion this year followed by $318 billion in the following year. Most notably, the company has set aside over $35 billion that it will use to repurchase its stock beginning in December.
Despite all this, Micron Technology is now one of the cheapest stocks in the S&P 500 Index. It has a forward price-to-earnings ratio of 5, much lower than the S&P 500 Index’s average of 19. In contrast, Nvidia, which has slower growth and lower margins, has a multiple of 21. Western Digital, another memory company, has a multiple of 24.
Micron’s valuation metric is also lower than other companies in the memory industry, like SK Hynix and Samsung Electronics. It is also lower than its five-year average of 74.
Additionally, Micron has one of the best rule-of-40 multiples. By adding its net profit margin of 63% and its forward revenue growth rate of 106%, its multiple is 169%.
The cheap valuation is because of the potential competition from Chinese companies like CMXT, and the fact that the memory industry is highly cyclical.
Micron Stock Price Technical Analysis
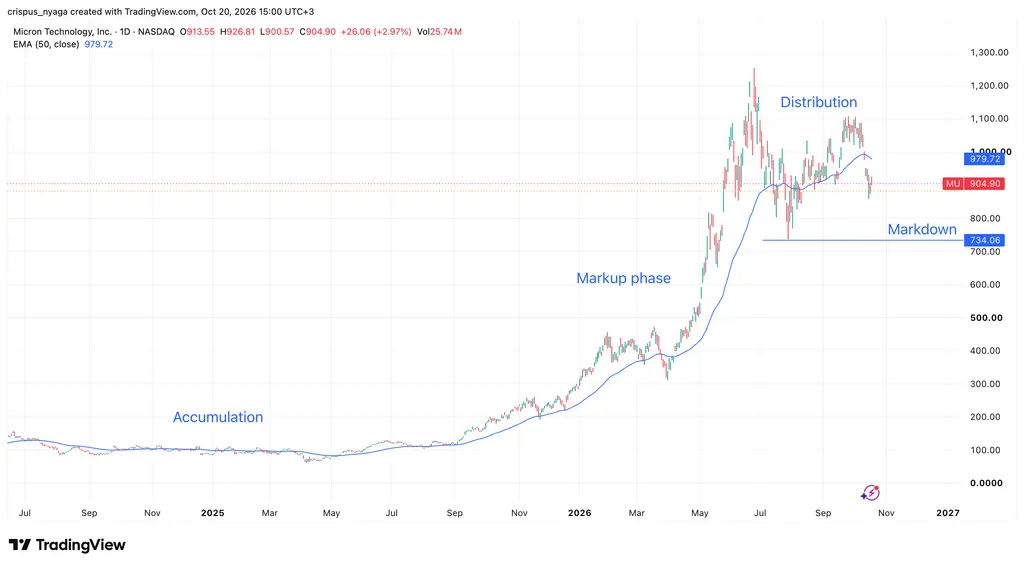
MU stock chart | Source: TradingView
The best way to explain the ongoing Micron stock retreat is the Wyckoff Theory. This theory identifies four stages that assets go through: accumulation, markup, distribution, and markdown.
A look at its condensed chart shows that the stock was in a tight range in 2024 and part of 2025. It then entered the markup phase in 2025 through June 25. Recently, however, there are signs that it has moved to the distribution and markdown phases, which are characterized by more selling.
Therefore, the stock will likely remain under pressure despite its cheap valuation. If this happens, it will likely drop to the support at $734.