

- easyJet shares (LON: EZJ) at 684.6p on 15 October, they are just below Apollo’s cash offer of 715p
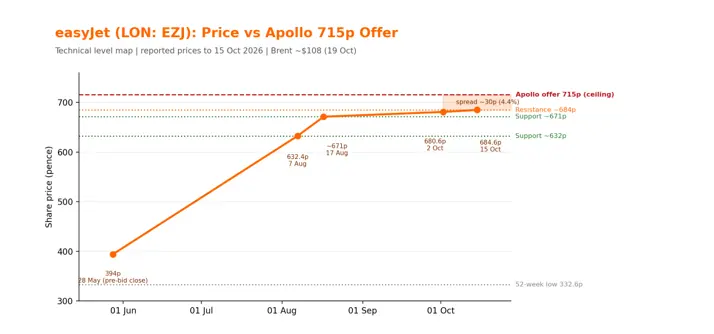
easyJet shares (LON: EZJ) are behaving as if they are a bond with an expiry date. With the shares at 684.6p on 15 October, they are near the top of their 52-week range and just below Apollo’s cash offer of 715p. That narrows the focus of this chart from airline fundamentals to deal mechanics, regulators and oil.
Where the Stock Has Come From
The rally is dramatic. On 28 May, the day before the bid period opened, shares closed at 394p and when Apollo’s terms were revealed on 7 August, they traded at 610.4p. They were last seen at 680.6p on 2 October, compared to a 52-week low of 332.6p and holders are up about three quarters from the undisturbed price of 394p which has dulled selling pressure as the share approaches the offer.
The Apollo Offer: What it Is and Why It Defines the Chart
Apollo has offered 715p per share, valuing easyJet at around £5.7 billion and an 81% premium to the 394p close on May 28.
Our guide to Apollo’s £5.7 billion takeover explains what it means for shareholders today. Rival bidder Castle Lake has withdrawn, although the board once backed Castle lake’s £5.5 billion proposal, showing how quickly sentiment shifts. The gross spread of c30p, or 4.4%, comes more from time value and completion risk than any traditional chart pattern
Key Technical Levels
The deal remains in place but 715p is now a hard ceiling. The area of 684p serves as the first resistance. Below them, support comes in near 671p as shares traded in mid-August followed then by the early August level at 632p. We have positive momentum, but price is not breaking out, rather compressing. A sustained move up above 715p would suggest the market sees a higher bid in play, something which seems highly unlikely.
Risks and Scenarios
Shareholder votes are on 11 November, with completion aimed at before the end of Q1 2027. European unions have objected and regulators must be convinced majority European ownership is maintained. The European Works Council has expressed its discontent with limiting commitments to staff to just twelve months and promises without binding character. They would have to bring patience testing delays with an even wider spread.
Failure could send shares back toward pre-bid levels, and our earlier piece on the 400p minefield examined that zone. The next listed earnings date is 1 December.
Outlook
Slow grind to 715p as approvals arrive is the base case The downside risk is a failure to regulate or vote. The view is that dips towards 671p will lure merger-arbitrage buyers for as long as the timetable stands, but a move below 632p would indicate market skepticism over completion. Consider treating easyJet as a straightforward event-driven play so position size modestly, monitor both levels closely.