

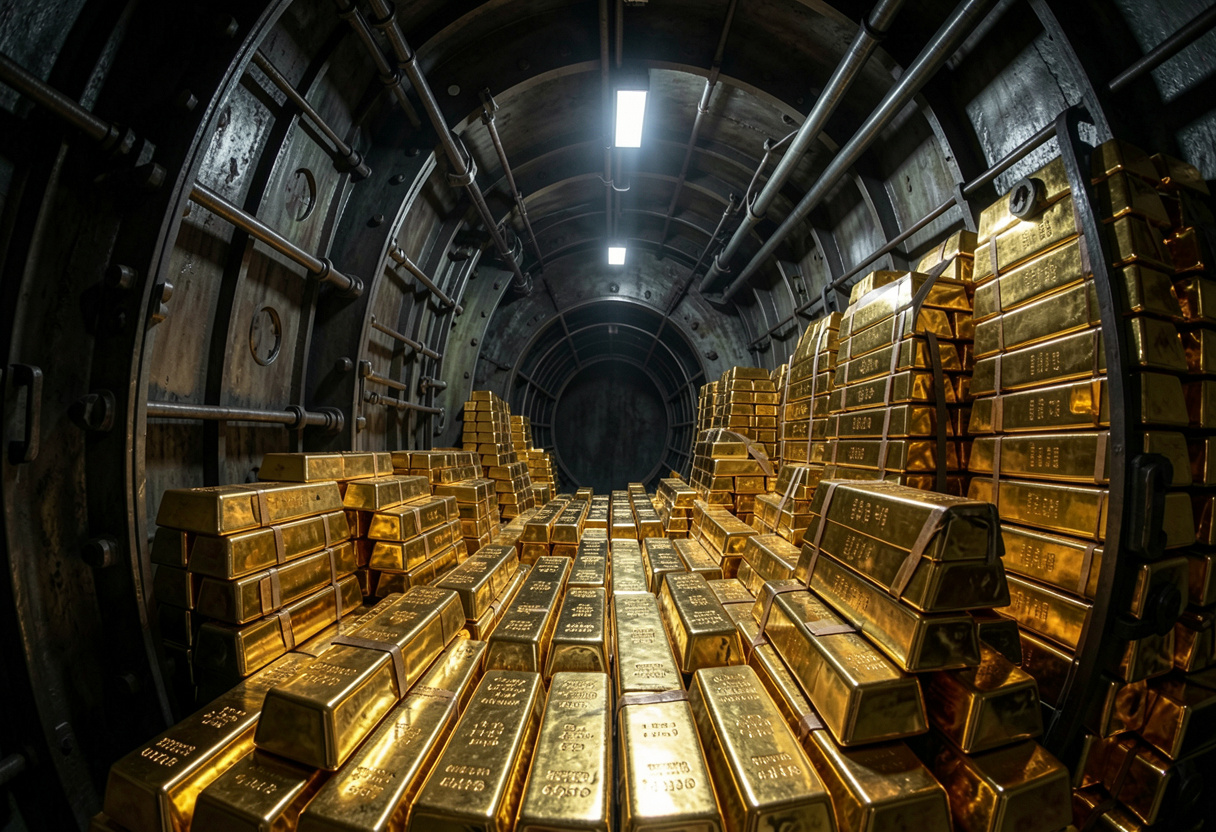
- Gold's still having a tough time in 2026, down over 3% this year and nearly 4% just this month. High US Treasury yields simply offer more appeal than factors that typically support the precious metal.
- Even with rising national debt, political friction in France, and wider geopolitical risks, investors are choosing high risk-free yields over gold's traditional role as an inflation hedge.
- US mid-term elections could shift this if fiscal or political outcomes push yields lower. Should that occur, gold's current prices might start to appeal to patient, long-term buyers.
Last year, gold performed exceptionally well, making its current decline a notable shift. The precious metal is down over 3% this year, with the XAUUSD pair alone shedding almost 4% last month. By mid-October, an ounce fetched around $4,170-$4,180.
A primary driver of this trend has been elevated US Treasury yields. The benchmark 10-year yield recently approached 5.07%, increasing the opportunity cost of holding assets that do not generate income, such as gold.
This is happening even though factors that usually support gold prices are not just present, but strong. They include high inflation, political uncertainty in France, rising US national debt, and ongoing geopolitical tensions. Normally, these would push investors toward safe-haven assets like bullion.
The situation presents a divergence where gold, a traditional safe haven, is experiencing weakness amid concerns over war, debt, and inflation. We discuss what this means and how it could play out.
Yields Are Winning the Argument
Gold doesn’t pay interest, so it struggles when other safe assets offer better returns. Earlier this month, both 10-year and 30-year Treasury yields hit 24-year highs. When real yields are this high, investors usually prefer interest-bearing government debt over gold.
In addition, institutional investors are getting over 5% annual yields on short-term US Treasuries. That makes holding physical gold much less attractive.
Even with growing budget deficits in the US and France, the US dollar remains the world’s main reserve currency. Investors seem to be prioritizing high, risk-free interest rates over protecting against inflation.
Are investors over-trusting the dollar?
To some extent, yes, because the underlying issues are significant. While market stress in French bonds and rising worries about US Treasuries have created some demand for safe havens, the dollar became the main refuge because of its higher yields. It even hit a one-year high before pulling back a bit. The dollar index recently neared 103.00.
Debt concerns have grown in both the United States and France. France’s government debt is almost 119% of GDP, and its deficit is over 5%. This has driven French 10-year yields to near multi-decade highs, making the spread over German bonds wider.
As France deals with budget issues and higher borrowing costs, European bond markets are showing strain. A lasting rise in sovereign risk premiums across major economies might eventually weaken trust in fiat currencies. This could help gold’s long-term prospects, even if its short-term path stays volatile.
The video below done discusses US September inflation data and its implications on Federal Reserve interest rate policy, bond yields, major currency pairs and gold prices.
Could US Mid-Term Elections Impact the Trend?
The US mid-term elections on November 3 bring more uncertainty. Markets already expect possible shifts in congressional control, which might change the fiscal outlook.
Historically, gold prices often rise in the month before mid-term elections, while the dollar frequently weakens. This pattern appeared in the five mid-term elections from 2006 to 2022.
Any election outcome pointing to larger structural deficits or less policy certainty could put downward pressure on the dollar and yields, giving gold a chance to recover. But if voters favor fiscal discipline, yields might stay higher for longer.
If the mid-term elections create congressional gridlock, legislative roadblocks could curb aggressive government spending. This situation might lower long-term yield expectations and take away a major obstacle for gold.
Alternatively, if political instability grows, capital looking for safety could quickly shift from dollar holdings into bullion.
What Should Investors Do About It?
Pinpointing the best time to buy gold is tough. We could see a sharper price drop if yields keep climbing or if the dollar gains strength from surprisingly good economic news.
Bank of America expects gold prices to dip below $4,000 in the next three months. Bullion’s barely held above that mark since August.
Meanwhile, Goldman Sachs upped its estimate for central bank demand, now seeing roughly 60 tonnes per month. Yet, they also cut their year-end price target by $500 back in June, showing just how much forecasts can shift. ANZ, on the other hand, thinks gold might break $5,000 by 2027 if yields and the dollar weaken.
One measure approach would involve spreading out purchases. Say someone plans to put $9,000 into gold. They could invest $3,000 today, another $3,000 after the election, and the final $3,000 following the December Federal Reserve meeting. This method helps spread out timing risk instead of betting everything on one moment.
Gold loses its incentive when Treasury yields climb and the dollar gets stronger, mainly because it doesn’t offer a yield itself. Also, high inflation usually pushes up expectations for Fed rate hikes.
Concerns over France’s increasing yields and deficits signal sovereign risk. This kind of situation can actually help gold, as investors often look for assets not tied to government debt.
Should the elections result in more political gridlock or larger deficits, we could see the dollar and yields fall. That might then help gold prices bounce back after the vote.