
Archived Article This article was published more than 5 months ago. The market data, prices, forecasts, and analysis were accurate at the time of publication but may have changed since then. Please use this article for historical reference only and refer to our latest content for current market information.
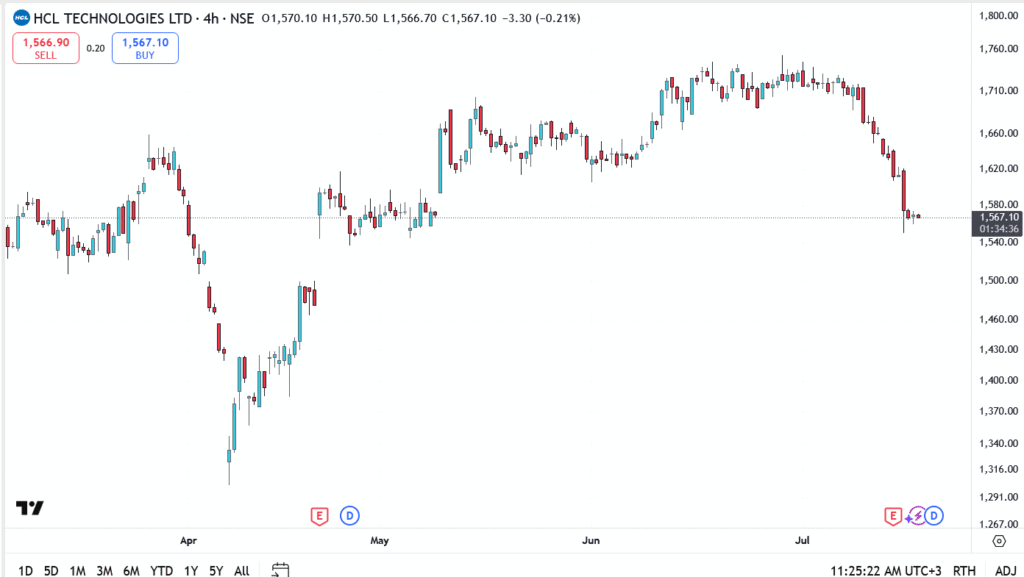
HCL Technologies share price was slightly lower on Wednesday, hovering near ₹1,567 in early trading. The stock has remained under pressure since last week’s Q1 earnings miss, slipping beneath the ₹1,600 level with no strong signs of a bounce. While the initial slide was sparked by the weak quarterly print, price action suggests sellers are still calling the shots.
HCL Tech reported a 9.7% drop in net profit for the June quarter, coming in at ₹3,534 crore, while revenue growth stood at a modest 2.1%. The results didn’t inspire much confidence, particularly in contrast with the stronger performance posted by TCS and Infosys. Investor sentiment took a further hit after the company trimmed its full-year revenue growth forecast to 3–5%, down from the earlier projection of 5–7%.
Adding to the bearish tone, several brokerages cut their ratings in response. CLSA moved from ‘Buy’ to ‘Underperform’, while JPMorgan and Kotak flagged weak product traction and limited near-term growth visibility. That cautious tone is now clearly being priced in.
HCL Technologies Share Price Prediction
HCL Technologies share price is currently pivoting at ₹1,566, with price action below this level signaling further pressure. If sellers maintain their grip, support could emerge around ₹1,540, followed by a deeper downside target at ₹1,480.
On the other hand, a recovery above ₹1,600 is needed to shift momentum back in favor of the bulls. Clearing that level could open the door to ₹1,620, and potentially ₹1,660 if buying accelerates.
For now, short-term sentiment remains cautious. However, the long-term picture isn’t off the table, if HCL can rebuild its growth visibility and steady its margin outlook in H2, a turnaround case may still be on the cards.