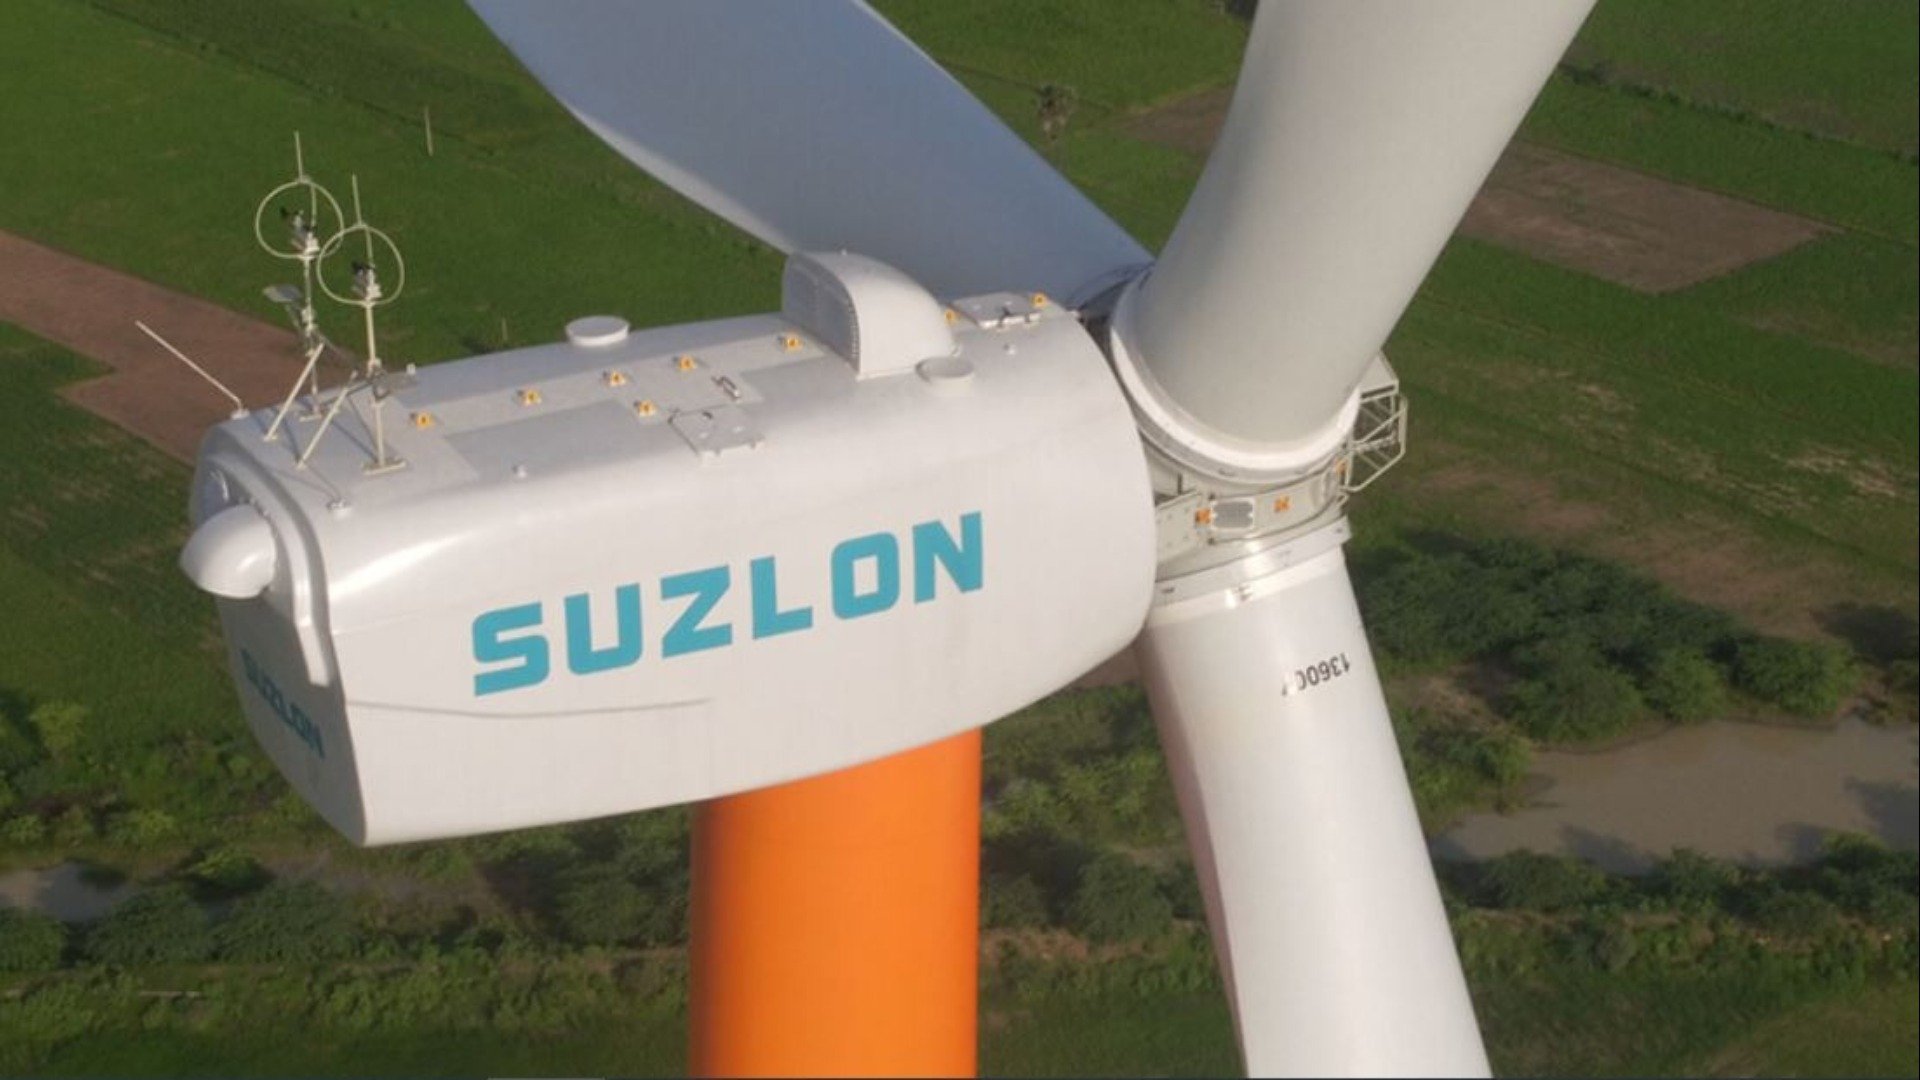
- Suzlon Energy stock has fallen over 10% last month and about 27% in the past three. This decline mainly comes from Q1 margin compression, despite the company's strong revenue growth and a healthy 6.1 GW order book
- While weaker profitability partly explains the sell-off, the shares' drop appears overdone. The company maintains a net-cash balance, is on track for record FY26 deliveries, and benefits from India's natural demand for wind energy.
- Near-term resistance sits around ₹46. However, strong technical support between ₹38 and ₹40, along with rising delivery volumes, suggests a steady recovery is likely over several months.
Suzlon Energy shares have been under steady pressure since late June, trading near ₹42 by mid-September 2026 after falling over 10% last month. The stock is down about 27% over three months, has lost 20% year-to-date and roughly 28% in the last year, sitting well below its 52-week high of around ₹61.50.
This drop follows a remarkable turnaround, where the company went from being deeply in debt to becoming a net-cash leader in renewable energy.
Is the Drop Justifiable or an Overreaction?
Suzlon’s recent stock dip appears driven by a blend of business realities and market sentiment. There are good reasons for this decline.
Shrinking margins during a high-growth period raise questions about the company’s cost management, its move toward more Engineering, Procurement, and Construction (EPC) contracts, and its short-term profitability.
Suzlon’s first quarter fiscal year 2027 results revealed revenue climbing over 22% year-on-year, reaching ₹3,819 crore. Still, EBITDA margins narrowed to 15.6%, down from 19.2% in the same quarter last year.
Net profit fell about 6% to ₹305 crore. This was due to investment costs for the “Suzlon 2.0” initiative, higher supply chain and logistics expenses, and broader industry hurdles like tough land acquisition and grid transmission infrastructure problems.
Investors reacted to the tighter margins and quarterly profit decline, even with the company’s robust 6.1 GW order book, which includes substantial work from public sector undertakings and commercial and industrial clients.
A stock price drop of more than 25% from its 52-week high could signal an overcorrection. The market seems too focused on temporary margin pressures, perhaps missing Suzlon’s strong, debt-free finances and large order book.
Recent orders, like a 200 MW project from Ayana Renewable Power, along with India’s steady demand for wind energy, set a strong base for future growth.
Many brokerage firms, even as they lower near-term earnings estimates, still see positive long-term prospects. This suggests the market might have overemphasized one weaker quarter’s impact.
Is a Near-Term Recovery Feasible?
Technically, the stock is nearing an important support level, between ₹38 and ₹40, where long-term investors have historically shown interest.
Although important moving averages still point to a bearish trend, high delivery volumes suggest institutional investors and long-term capital are accumulating shares, not selling off in a panic.
Ongoing new orders, better project execution, and positive developments in cost management over the next few quarters could help bring back investor confidence. Supportive renewable energy policies and addressing sector infrastructure issues would also contribute.
What Should Investors Focus On?
Instead of getting caught up in daily price swings, investors should watch for profit margins to recover as supply chain issues, especially those tied to the Middle East, start to ease.
Investors should also keep an eye on how quickly Suzlon turns its 1,257 MW of installed but uncommissioned inventory into billed revenue. It’s also worth tracking how its “Suzlon 2.0” diversification into solar and Battery Energy Storage Systems (BESS) is progressing.
These operational indicators, more than short-term market sentiment, will tell us if this current dip offers a buying opportunity or signals a bigger downturn.
The stock fell sharply due to margin compression in Q1 results, profit-booking after a strong rally over several years, and technical weakness below key moving averages.
Yes it does, due to lower profitability and margin pressure. However, the company’s strong order book and improved balance sheet suggest the sell-off might be overdone given its long-term prospects.
Sequential margin improvement, stronger project commissioning, sustained order inflows, and a technical breakout above resistance near ₹46 are among the things that could help the shares bounce back quickly.